Your credit score is a critical factor in determining your eligibility for a loan against property (LAP). This secured loan allows borrowers to pledge their residential or commercial property as collateral in exchange for funds, which can be used for a variety of purposes such as business expansion, medical expenses, or higher education. While the collateral reduces the risk for lenders, your credit score still plays a significant role in influencing the loan approval process, interest rates, and terms. Below is a detailed explanation of how your credit score impacts your loan against property eligibility.
Role of Credit Score in LAP Eligibility
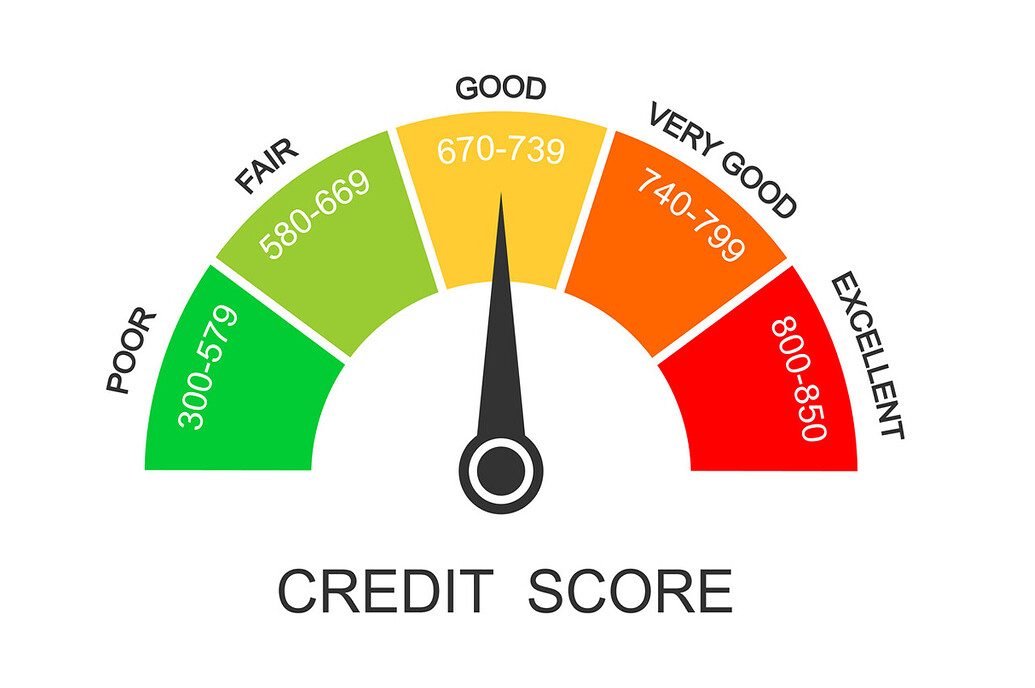
Your credit score reflects your financial behavior, creditworthiness, and repayment history. Lenders use it as a tool to assess the risk involved in lending you money. A high score (750 or above) indicates a strong repayment history, financial discipline, and low credit risk, making you a preferred candidate for a loan. Conversely, a low score raises concerns about your ability to manage debt, which could lead to rejection or unfavorable loan terms. Usually, there is no set criteria for the minimum CIBIL score for a loan against property. However, having a high score can help you get better loan terms.
Impact on Loan Approval
Lenders may view applicants with high credit scores as reliable borrowers. While collateral minimizes the risk in a loan against property, lenders still consider the credit score to ensure the borrower has a track record of repaying debts. A low score could result in loan rejection, even if the property’s value meets the loan requirements. On the other hand, a strong score improves your chances of approval.
Effect on Loan Amount Sanctioned
The loan amount sanctioned under a loan against property depends on the property’s market value and the loan-to-value (LTV) ratio, typically ranging between 60% to 75%. However, your credit score influences whether the lender sanctions the maximum possible amount. A low score may lead to a lower loan amount as lenders perceive greater risk.
Impact on Interest Rates
Your credit score significantly impacts the interest rate on a loan against property. Borrowers with high scores are often offered lower interest rates as lenders feel confident about timely repayments. In contrast, borrowers with low credit scores may face higher interest rates to compensate for the increased risk.
Repayment Tenure and Terms
A good credit score may also influence the repayment tenure and flexibility offered by lenders. With a high score, you may have access to longer tenures and favourable terms, allowing you to repay the loan comfortably. A low score, however, might result in stricter terms or shorter tenures, increasing the monthly repayment burden.
Eligibility for Additional Features
Some lenders provide additional features like overdraft facilities, balance transfer options, or top-up loans to borrowers with strong credit scores. These features can make loan management easier and more cost-effective. A low score may disqualify you from availing of these benefits.
How a Low Credit Score Affects Your Application
Increased Scrutiny
Borrowers with low credit scores often face stricter scrutiny during the application process. Lenders may require additional documentation or collateral to mitigate the risk.
Higher Risk of Rejection
A low score signals a higher risk of default, making lenders less inclined to approve your application, even if you meet other eligibility criteria.
Limited Loan Options
With a poor credit score, your options may be limited to lenders willing to take on high-risk borrowers. These loans typically come with higher interest rates and stricter terms.
Improving Your Credit Score to Qualify for an LAP
If your credit score is low, there are ways to improve it before applying for a loan against property:
Pay Existing Debts on Time
Ensure timely repayment of existing loans and credit card bills to demonstrate financial discipline.
Lower Your Credit Utilisation Ratio
Keep your credit usage below 30% of your available limit to showcase responsible credit behaviour.
Avoid Frequent Loan Applications
Limit credit card or loan applications to avoid hard inquiries, which can temporarily lower your credit score.
Check Your Credit Report for Errors
Review your credit report for inaccuracies or discrepancies and get them corrected to improve your score. Also, check your CIBIL score regularly.
Opt for Secured Credit
Use secured credit options, such as credit cards against fixed deposits, to gradually rebuild your score.
Benefits of a High Credit Score for LAP
A strong credit score offers several advantages when applying for a loan against property:
- Faster Approvals: Lenders process applications faster for borrowers with good credit scores due to lower perceived risks
- Lower Interest Rates: A high score gives you access to competitive interest rates, reducing the overall cost of borrowing
- Higher Loan Amounts: Lenders are more likely to sanction the maximum loan amount based on your property’s value if your credit score is strong
- Flexible Terms: Borrowers with high scores often receive favorable repayment terms and access to additional features like top-up loans
Your credit score is a crucial factor that impacts your eligibility for a loan against property, influencing approval chances, loan amount, interest rates, and repayment terms. While a low score can pose challenges, it’s not an insurmountable barrier. Taking proactive steps to improve your credit score and presenting a strong overall financial profile can enhance your chances of securing favorable terms on a loan against property.