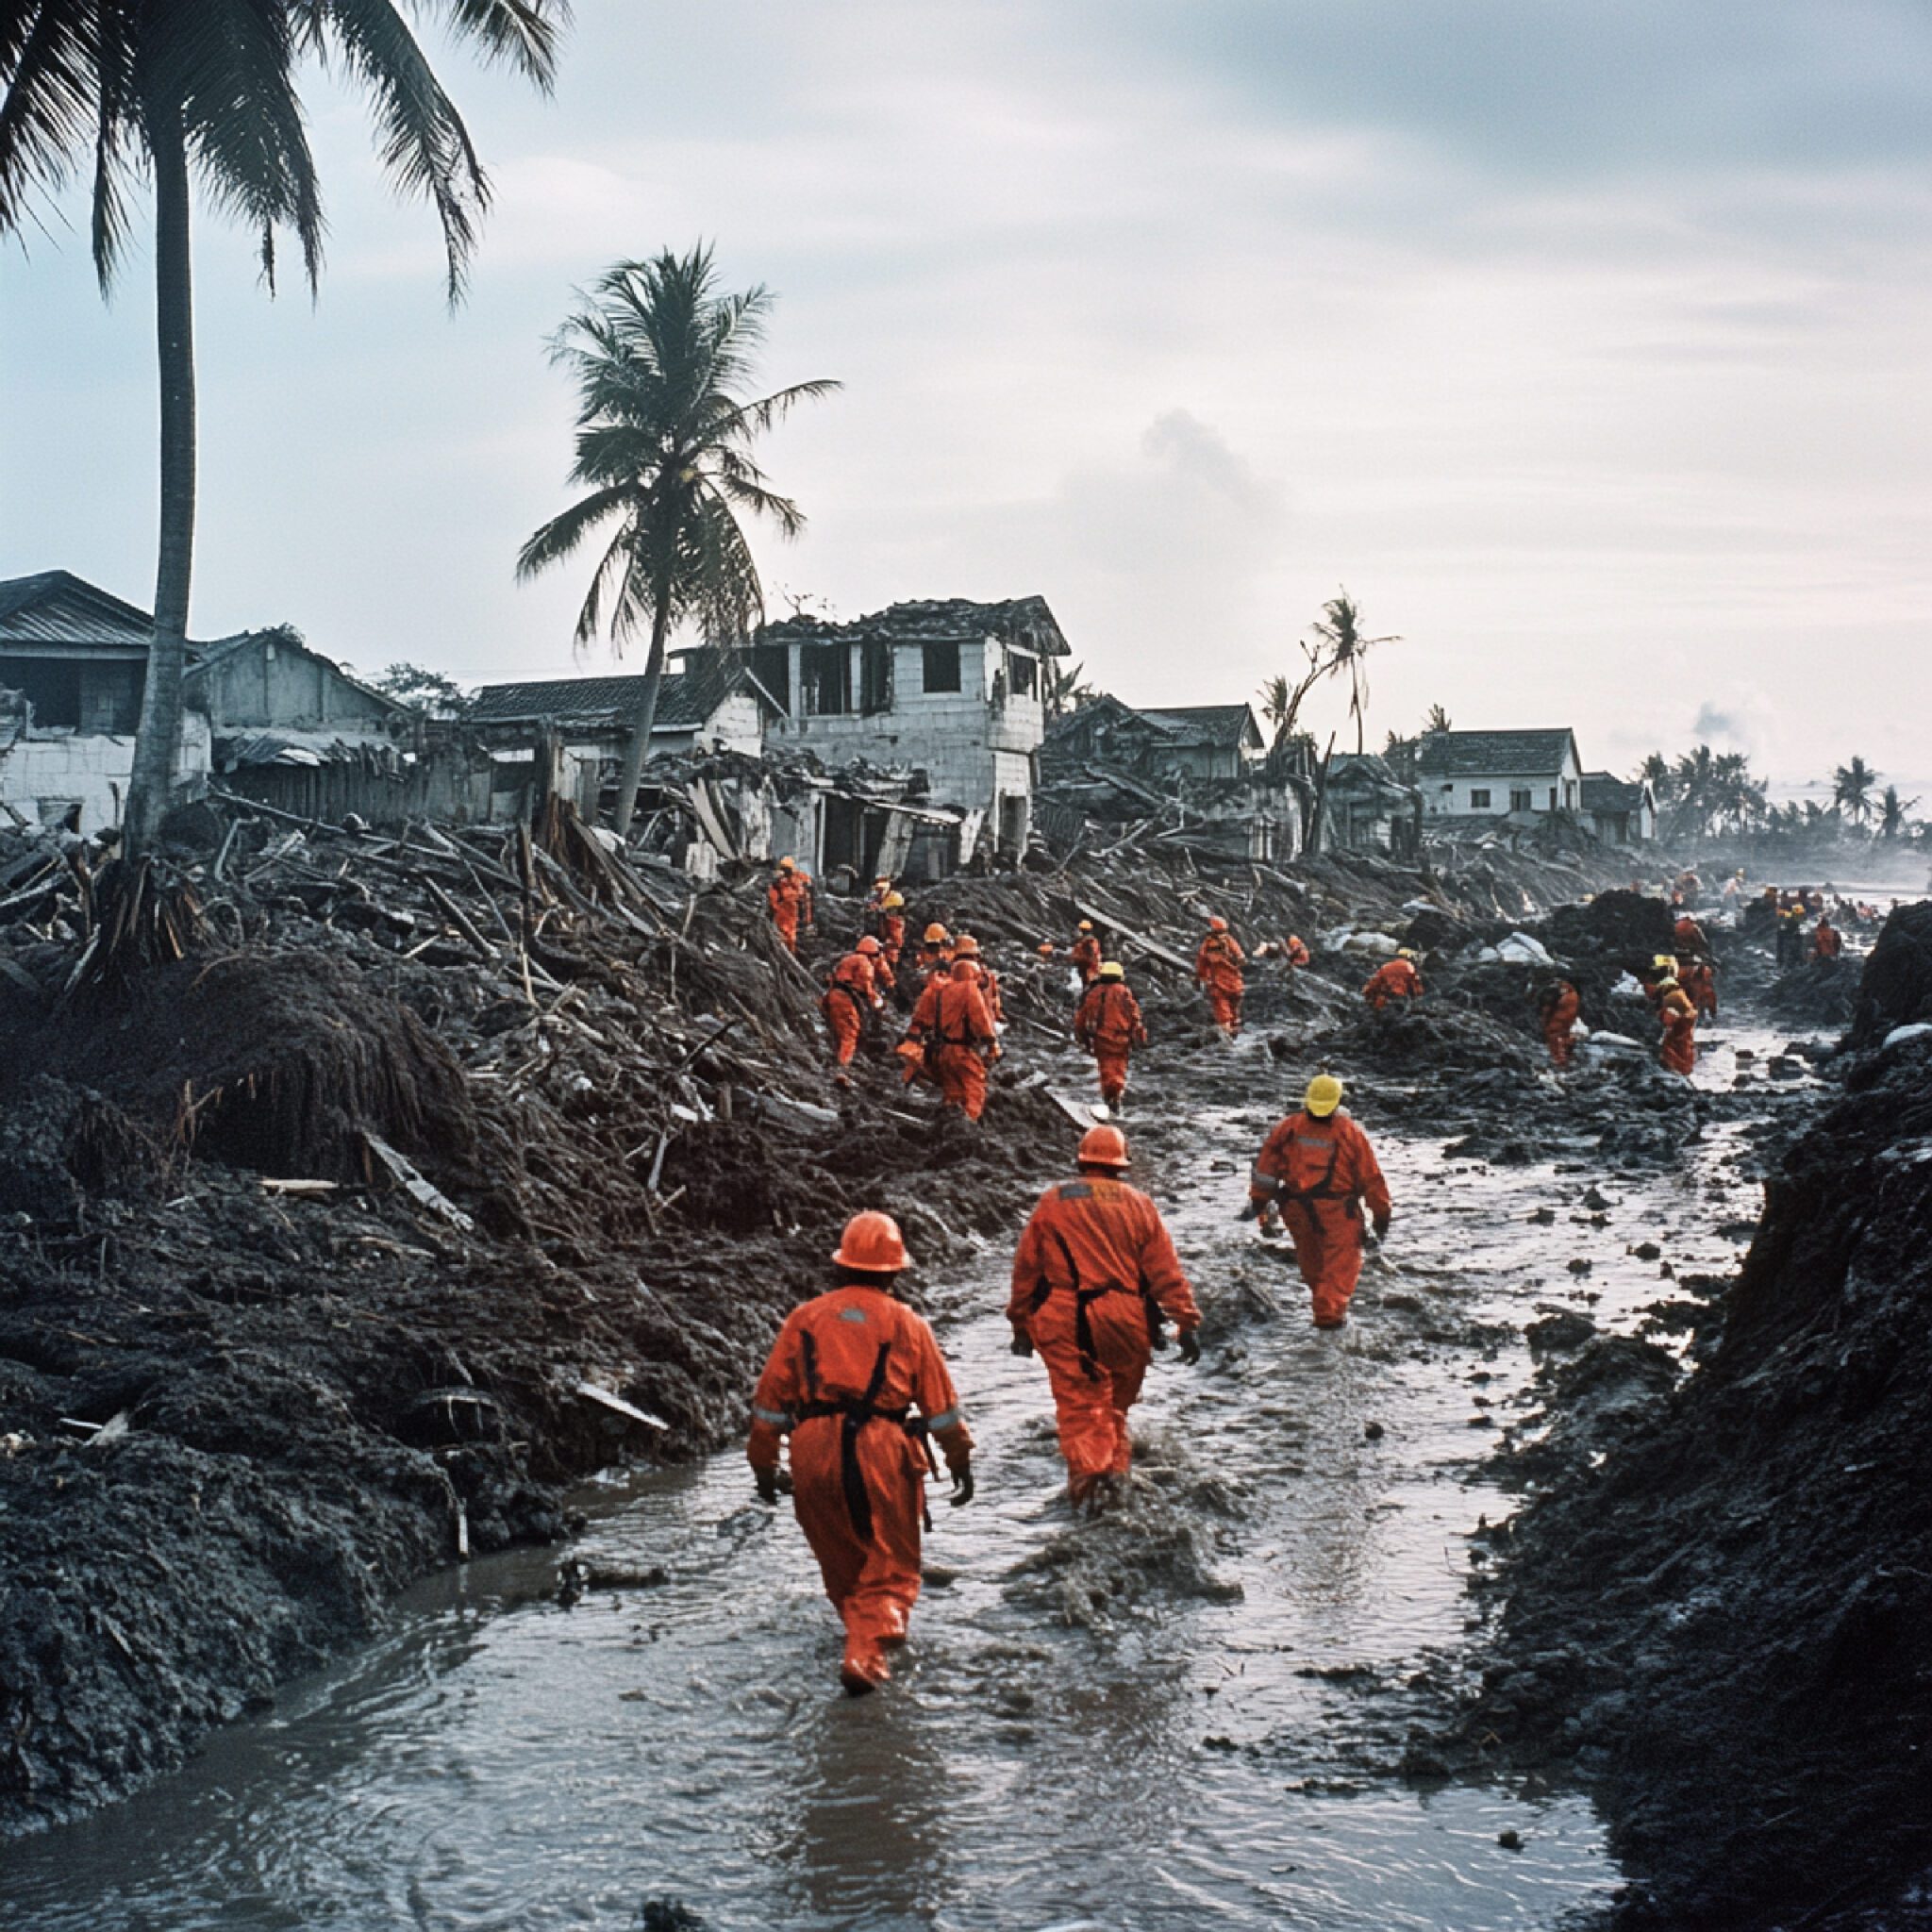
In 2024, the United States faced 27 separate weather and climate disasters that each caused more than $1 billion in damage.
That made 2024 the second-highest year on record for billion-dollar disasters. Nature does not send a calendar invite, and your wealth plan does not get a rain check.
Disasters Do Not Just Damage Houses
A fire, flood, hurricane, or tornado can hit more than your roof. It can wreck cash flow, delay retirement contributions, force debt use, and push major goals off track. That is why a wealth plan needs more than market charts and good intentions.
It also needs a disaster playbook. In that playbook, a professional property restoration company fits into the recovery side, but the bigger issue sits in your balance sheet: liquidity, insurance, taxes, document access, and income stability.
A lot of people assume a disaster turns into “someone else will handle it.” That sounds nice. It also sounds like a fantasy written by your deductible.
The Real Wealth Hit Usually Comes From The Gaps
Most people do not lose long-term wealth from one dramatic headline moment. They lose it through gaps.
Maybe the home stays uninsured for flood damage. Maybe the emergency fund looks fine until the hotel bill, cleanup costs, spoiled food, missed workdays, and higher insurance premiums show up like uninvited cousins.
Flood coverage causes one of the biggest surprises. Most homeowners’ insurance policies do not cover flood damage, which means a family can hold a perfectly normal policy and still face a brutal out-of-pocket bill after one storm.
At the same time, the insured U.S. natural catastrophe losses reached $115.6 billion in 2024. Huge losses do not always mean your specific losses have full coverage.
That gap can force people to sell investments at the worst time, tap retirement accounts early, or pile high-interest debt onto an already stressful month.
Cash Flow Matters More Than People Think
Long-term wealth plans usually focus on growth. Fair enough. Growth feels exciting. Emergency plumbing bills from a wildfire evacuation do not.
But after a disaster, cash flow becomes king. You may need money for temporary housing, travel, food, storage, repairs, insurance deductibles, and replacement items before any reimbursement arrives.
Keep an emergency fund because disasters often create immediate costs for hotels, transportation, food, and medical needs.
A weak cash buffer can turn a temporary disruption into a multi-year setback. That is where wealth plans start to wobble.
Your Investments Can Suffer From Bad Timing
Natural disasters do not only hurt physical property. They can force ugly financial timing.
If your home needs urgent work, your job pauses, or your small business shuts down for weeks, you may sell investments during a downturn just to cover repairs and living costs. That choice can lock in losses and reduce future compounding.
Retirement accounts can suffer, too. Missed contributions matter more than many people think, especially across a long timeline. Skip six months or a year, and you do not just lose those deposits.
This is why disaster planning belongs inside a wealth strategy, not off to the side like some boring folder nobody opens. Risk management protects returns. It also protects options. And in finance, options matter a lot more than heroic optimism.
Insurance, Records, And Taxes Can Save You
A strong long-term plan needs three boring heroes: proper insurance, accessible records, and tax awareness. Boring heroes rarely get movie deals, but they do useful work.
First, review coverage before trouble hits. Check dwelling limits, replacement cost terms, deductibles, loss-of-use benefits, and flood or wildfire exposure.
Second, store insurance policies, IDs, bank details, and other key records in the cloud or a waterproof container. Keep copies of important family documents, insurance policies, identification, and bank account records in secure digital form or protected storage
Third, know the tax rules. People affected by federally declared disasters may qualify for filing extensions and may be able to claim a casualty loss deduction on a current or prior-year return, depending on the situation.
That will not erase the pain, but it can reduce the financial aftershock.
How To Build A Disaster-Ready Wealth Plan
Start with your emergency fund. Aim for enough cash to handle your deductible plus several weeks or months of disrupted life. After that, audit your insurance line by line.
Do not assume.
Assumptions make expensive hobbies.
Next, protect your documents. Keep digital copies of insurance records, deeds, tax returns, IDs, and account lists. Then review your income risk. If you own a business, depend on hourly work, or live in an area with high storm, wildfire, or flood exposure, build an extra cushion into your plan.
Finally, treat disaster prep as part of wealth management, not fear management. You are not “expecting the worst.” You are protecting the future version of yourself from making panicked money decisions in a miserable week.
Ready To Recover: Financial and Insurance Readiness
The Bottom Line
Natural disasters can derail a long-term wealth plan through uninsured losses, weak cash reserves, forced asset sales, missed investing years, and messy recovery costs. The good news? A lot of that damage becomes less severe with better preparation.
Build cash reserves, check your coverage, secure your records, and understand the tax and aid rules before you need them. The weather will always do weather things. Your plan should know how to fight back.