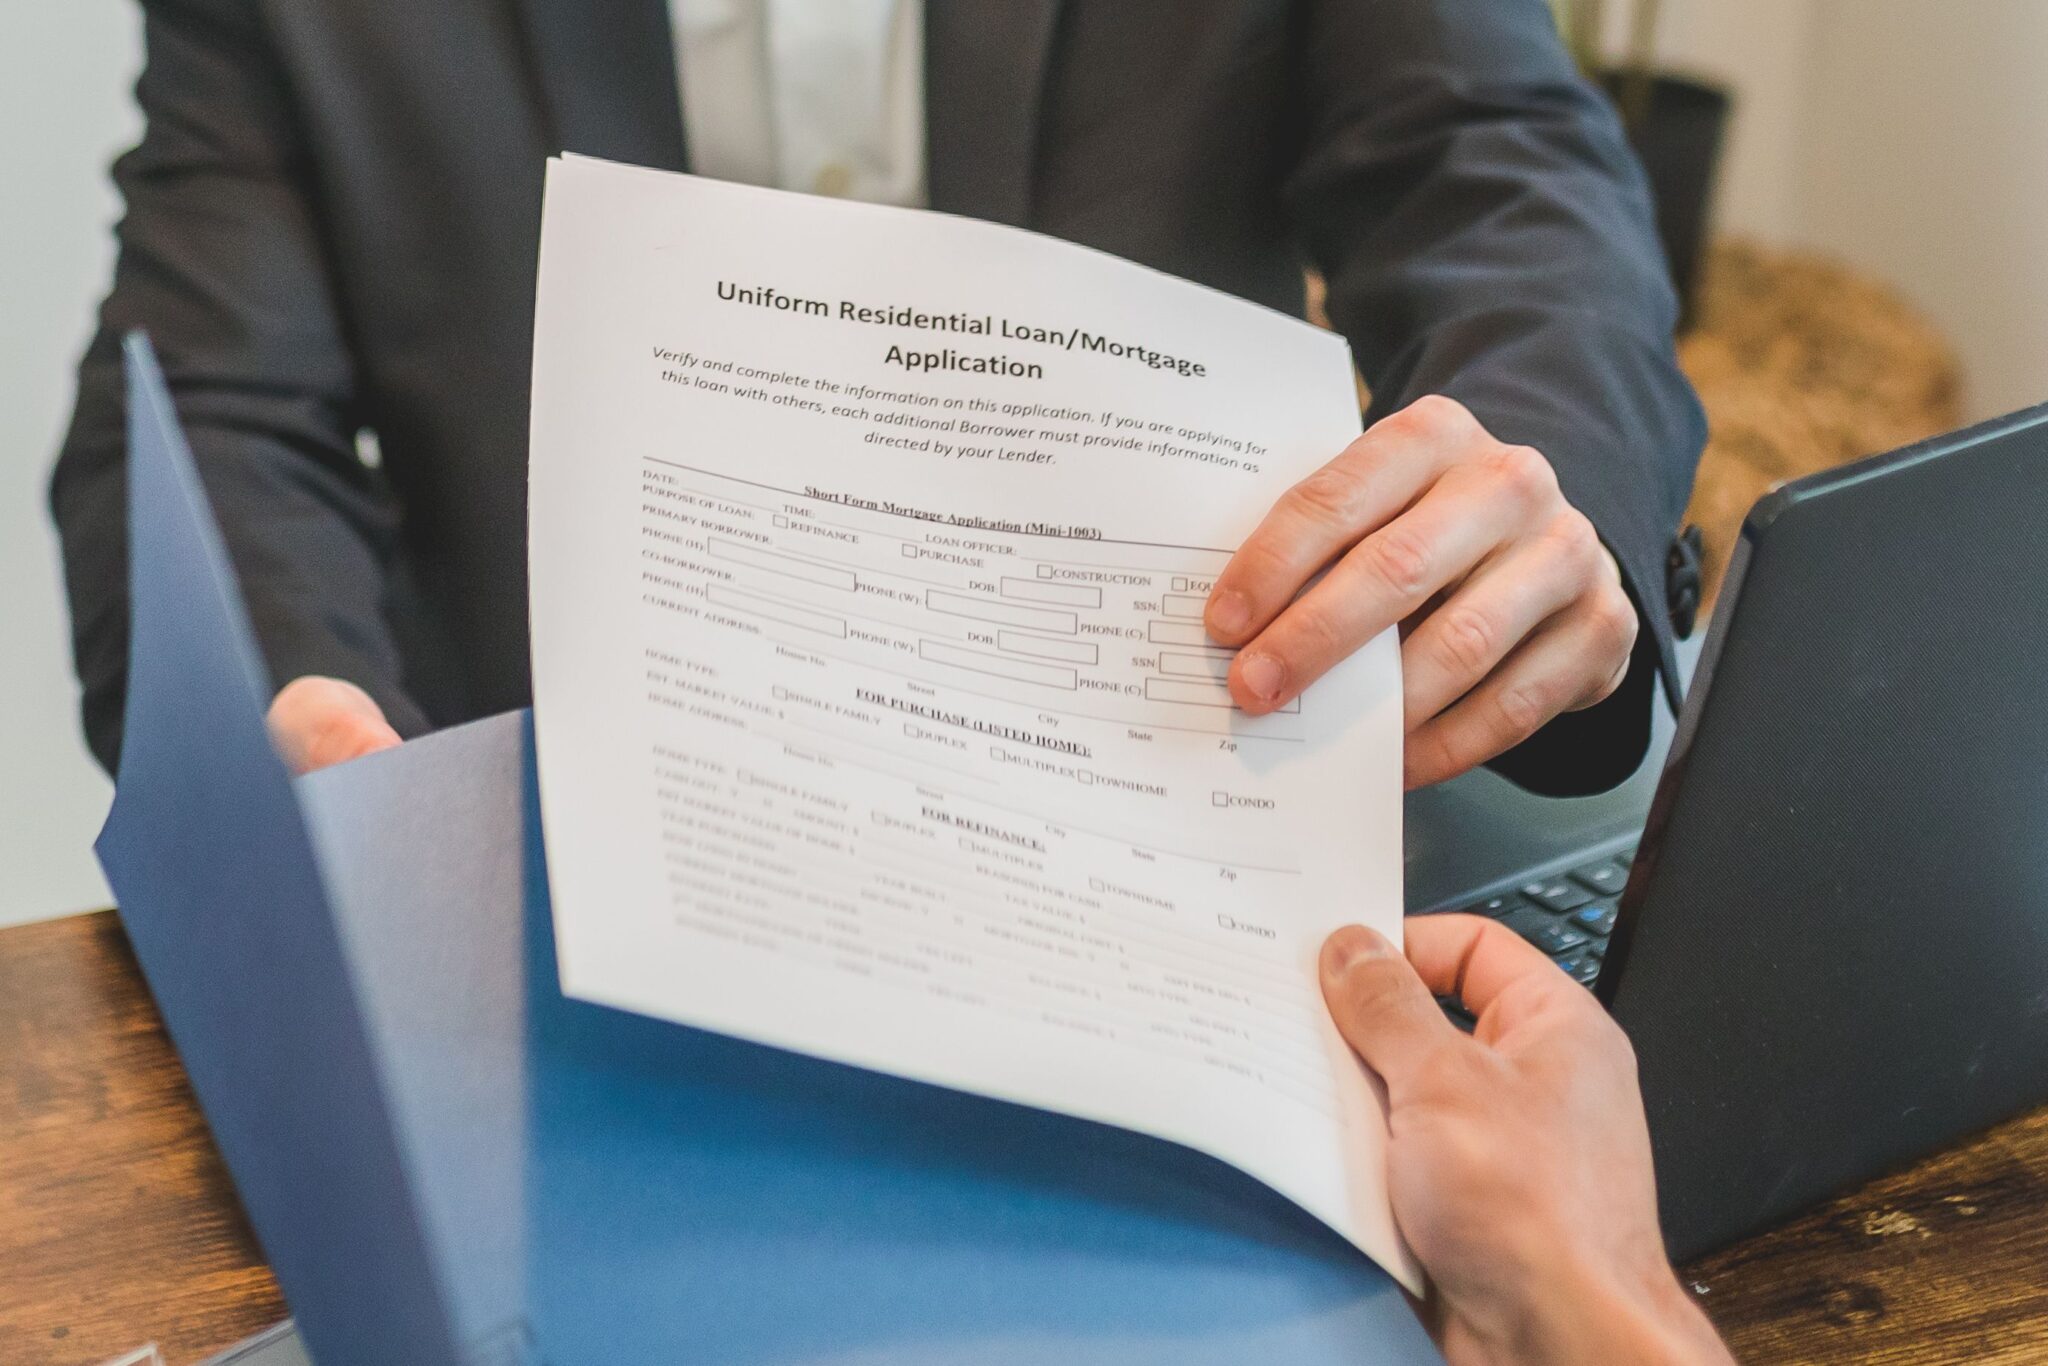
When a small business needs financing, most owners eventually run into the same fork in the road: an SBA loan or a conventional loan. Both can fund the same kinds of needs expansion, equipment, working capital, real estate—but the mechanics behind them are different enough that the choice can meaningfully affect approval odds, cost, and how quickly cash actually lands in the business.
Here’s how the two compare, and how to think about which one fits a given situation.
The Core Difference: Who’s Taking the Risk
A conventional loan is funded entirely by the lender, which bears the full risk if the borrower defaults. An SBA loan is still issued by a bank or other approved lender, but a portion of it commonly in the range of 50% to 90%, depending on the program—is guaranteed by the U.S. Small Business Administration. The government isn’t lending the money directly, it’s reducing the lender’s downside risk, which in turn makes the lender willing to extend credit on terms it might not otherwise offer.
That single structural difference is what drives most of the practical distinctions between the two.
Where SBA Loans Tend to Win
- More flexible qualification. Because the SBA guarantee absorbs some of the lender’s risk, SBA loans are generally more accessible to businesses with a shorter operating history, moderate credit, or less collateral than a conventional lender would typically require.
- Longer repayment terms. SBA loans can stretch out considerably longer than most conventional term loans, which can meaningfully lower monthly payments and ease cash flow, even if total interest paid over the life of the loan is a separate consideration.
- Broader allowable use of funds. SBA loans, particularly the 7(a) program, can generally be used for a wide range of business purposes, whereas conventional loans are often issued for a specific stated use.
- Lower down payment requirements in many cases, since the guarantee reduces how much the lender needs the borrower to have at risk upfront.
Where Conventional Loans Tend to Win
- Speed and simplicity. Conventional loans typically involve less paperwork and fewer approval steps, which can matter when a business needs funding on a tighter timeline. SBA loans, by contrast, usually take longer to close given the additional documentation and government guarantee process.
- Fewer restrictions on use and structure. Conventional lenders have more latitude to customize loan terms, and there’s no SBA program rulebook dictating eligible uses, size limits, or structure.
- Potentially lower cost for well-qualified borrowers. A business with strong revenue, an established track record, and excellent personal and business credit may be offered conventional rates that are competitive with—or in some cases better than SBA options, especially once SBA guarantee fees are factored in. SBA loans generally offer more attractive terms for borrowers who wouldn’t otherwise qualify for the best conventional rates, rather than automatically being the cheaper option across the board.
- No government eligibility criteria. SBA loans come with size standards, for-profit and U.S.-operation requirements, and other eligibility rules a business must meet. Conventional loans aren’t subject to those constraints.
A Few Things That Are Often Misunderstood
Personal guarantees aren’t unique to SBA loans. Most small business loans—SBA or conventional—require a personal guarantee from owners with significant equity in the business, particularly for newer or smaller companies. This is standard practice across both loan types, not a distinguishing factor.
“Easier to qualify for” doesn’t mean “no underwriting.” SBA loans still involve a real credit and financial review; the guarantee makes lenders more willing to extend credit to businesses that fall short of conventional standards, but it doesn’t eliminate underwriting altogether.
Neither option is fast by online-lender standards. Both SBA and conventional bank loans typically take weeks to close, not days. Businesses that need capital in a matter of days may need to weigh a bridge solution alongside either option, rather than expecting either path to move at online-lending speed.
How to Think About the Decision
A few questions tend to clarify which direction makes sense:
- Would the business qualify for competitive conventional terms today? Strong revenue, solid credit and an established operating history often mean conventional financing is simpler and just as cost-effective.
- Is cash flow tight enough that a longer repayment term matters? If stretching payments over more years would meaningfully ease monthly obligations, that favors SBA.
- How urgent is the timeline? If funding is needed quickly, the additional documentation and processing time for an SBA loan may not fit the situation.
- What’s the intended use of funds? More flexible general purpose needs may point toward SBA; a narrowly defined purpose might be just as well served by a conventional loan.
The Bottom Line
Neither option is universally “better”, they’re built for different situations. SBA loans exist largely to extend credit to small businesses that the conventional market might otherwise pass on, or to offer terms that ease cash flow for businesses that do qualify elsewhere. Conventional loans reward speed, simplicity, and strong qualifications. For most owners weighing small business loans the right starting point is an honest look at credit profile, timeline, and how the business plans to use the funds—then matching those realities to the loan type built to support them.