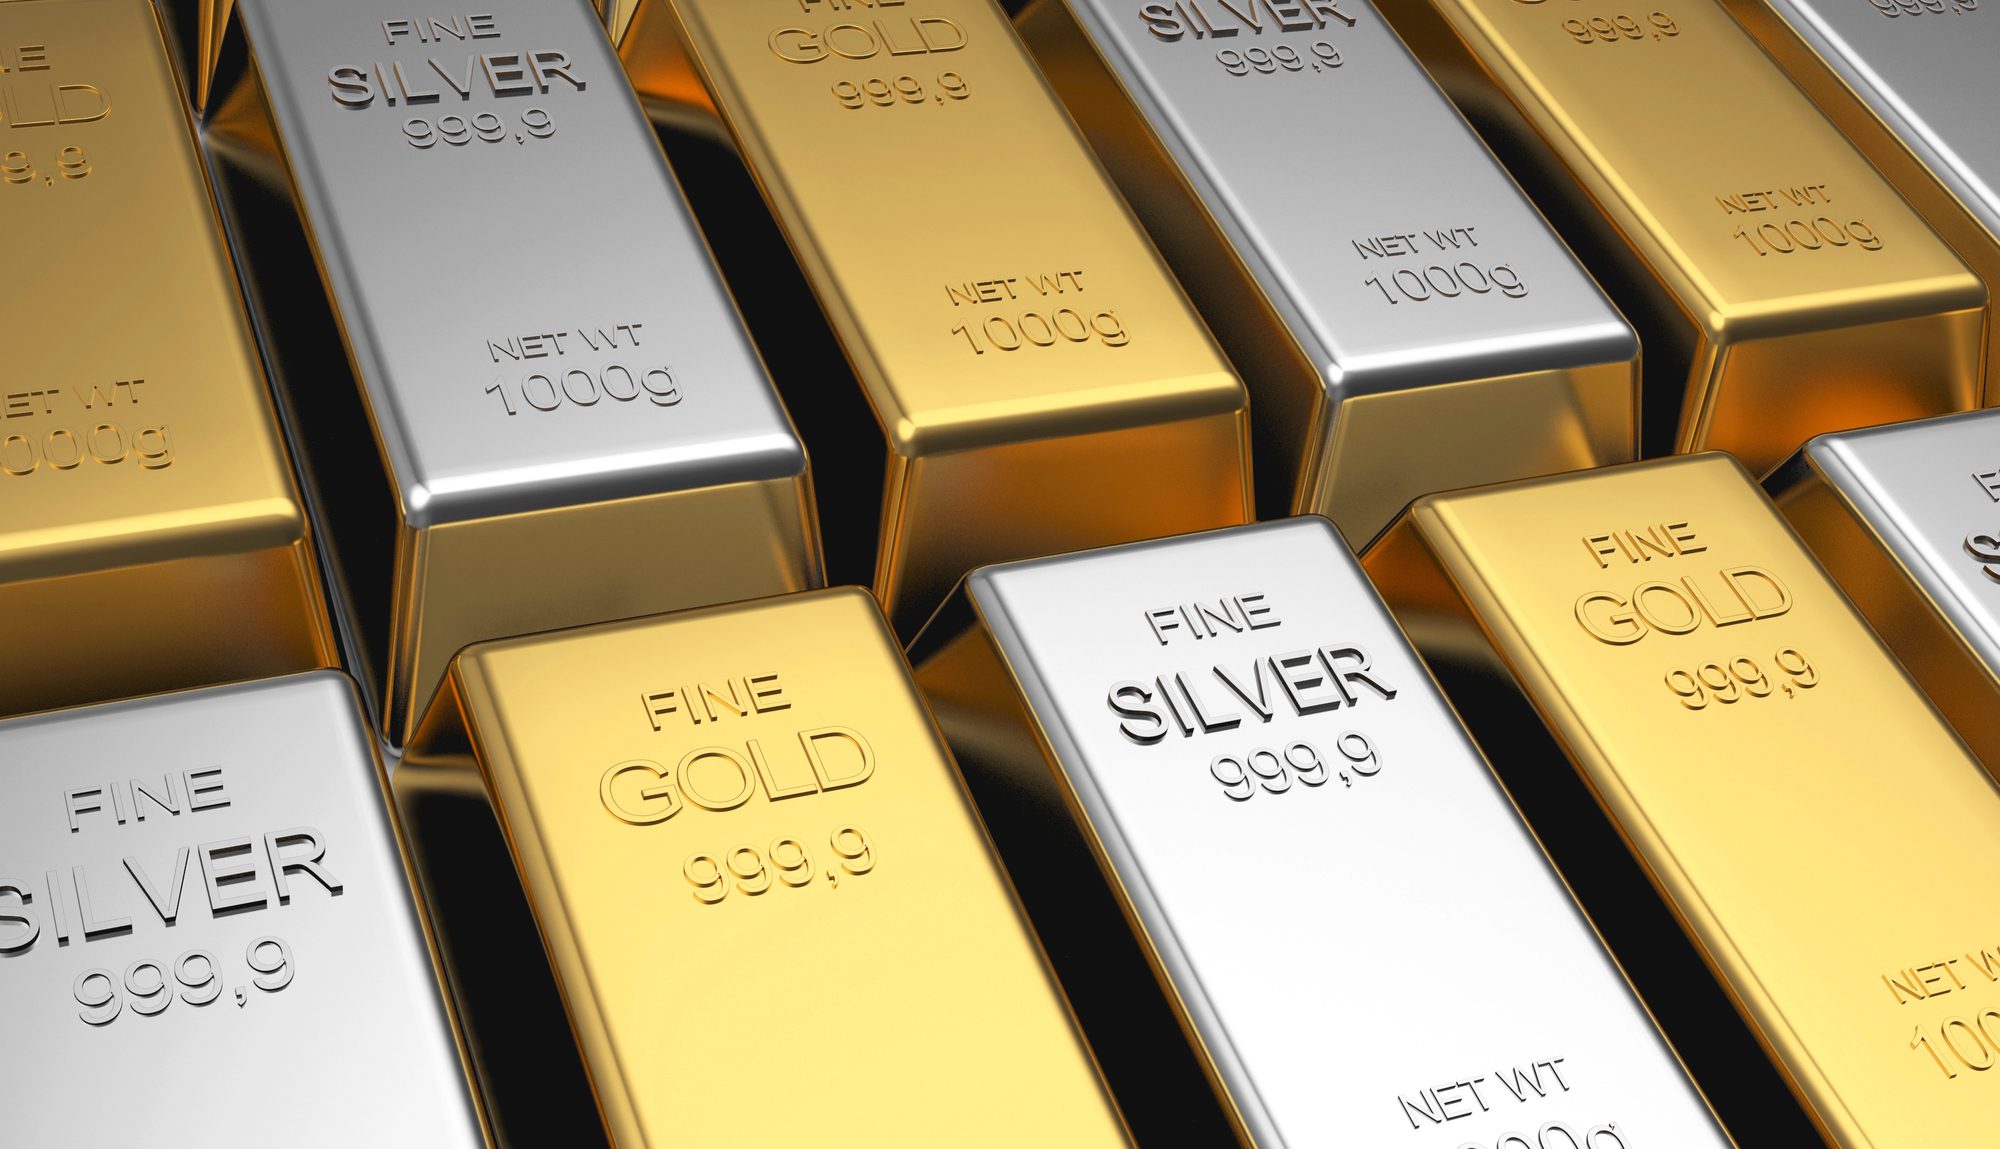
For investors focused on preserving wealth across decades rather than chasing the next quarter, the appeal of physical gold and silver is familiar. They are tangible assets, held outside the financial system, that have retained purchasing power through inflation, currency debasement, and periods of upheaval. Less widely understood is that you can hold them inside a tax-advantaged retirement account, pairing the diversification of physical metal with the tax treatment of an IRA. It takes a specific structure and carries real costs, but for the right investor it is a legitimate, long-established way to bring hard assets into a retirement plan.
Why physical metal belongs in the conversation
The case rests on the role metal plays rather than on a price forecast. Gold and silver hold a low correlation to stocks and bonds, which means they tend to hold or gain value in the conditions that pressure financial assets. They carry no counterparty risk, because they are not a claim on anyone’s solvency. Over long horizons they have preserved purchasing power against the slow erosion of currency. And for an investor thinking about legacy, physical metal is a durable asset that can be passed on. Those are the reasons a long-horizon, wealth-minded investor looks at metal in a retirement account, not short-term appreciation.
How the structure works
A precious metals IRA is a self-directed IRA, which differs from a standard brokerage IRA in what it is permitted to hold. A conventional account limits you to the securities your broker offers, which generally excludes physical bullion. A self-directed account, held with a custodian that specializes in alternative assets, expands the menu to include approved metals. The tax advantages are the same as any traditional or Roth IRA. Only the permitted holdings change. In practice there are three parts: a custodian that administers the account, a dealer that supplies the bullion, and an approved depository that stores it.
What qualifies, and what does not
The rules require investment-grade metal in approved forms. Bullion generally has to meet minimum purity thresholds, around 99.5 percent for gold and 99.9 percent for silver, and come as eligible coins or bars. Certain government-minted coins, including American Gold and Silver Eagles, qualify, alongside bars and rounds from accredited refiners that meet the fineness standard. Collectible and numismatic coins generally do not qualify, which is an important limit. The account is built to hold investment-grade metal, not rare coins.
The storage rule that surprises people
Metal held in an IRA cannot sit in a home safe. It must be kept at an approved depository, and arrangements that promise home storage of IRA metal have drawn scrutiny from tax authorities. The depository holds the bullion either segregated, meaning your specific metal is kept apart, or commingled, meaning it is pooled and you own a share. Segregated storage usually costs more. Either way, there are annual custody and storage fees that a brokerage account holding only securities would not charge.
The costs, stated plainly
A precious metals IRA carries setup fees, annual custodian fees, storage fees, and the usual premium over spot when the metal is bought. All of this is higher than the near-zero cost of holding an index fund. In exchange, you get physical metal with its diversification benefits and the tax treatment of a retirement account. Whether the trade is worthwhile depends on how large a metals allocation you want and how long your horizon is.
Fitting it into a wealth plan
Sized correctly, a metals allocation is insurance within a retirement portfolio, not its engine. Most long-horizon investors keep it to a modest share of the whole, enough to matter in a crisis without dragging on returns through the long stretches when risk assets are doing their work. Rebalance it on a schedule rather than on emotion, and treat it as one component of a diversified plan rather than a concentrated bet.
A note on advice
This is general information rather than tax or investment advice, and the rules around retirement accounts and precious metals are detailed and subject to change. Anyone considering this route should confirm current requirements with a qualified custodian and, where appropriate, a tax professional. With that caution stated, holding physical gold and silver in a retirement account is a legitimate and durable way to bring hard assets into the part of a portfolio built to carry long-term wealth.
photo by depositphotos