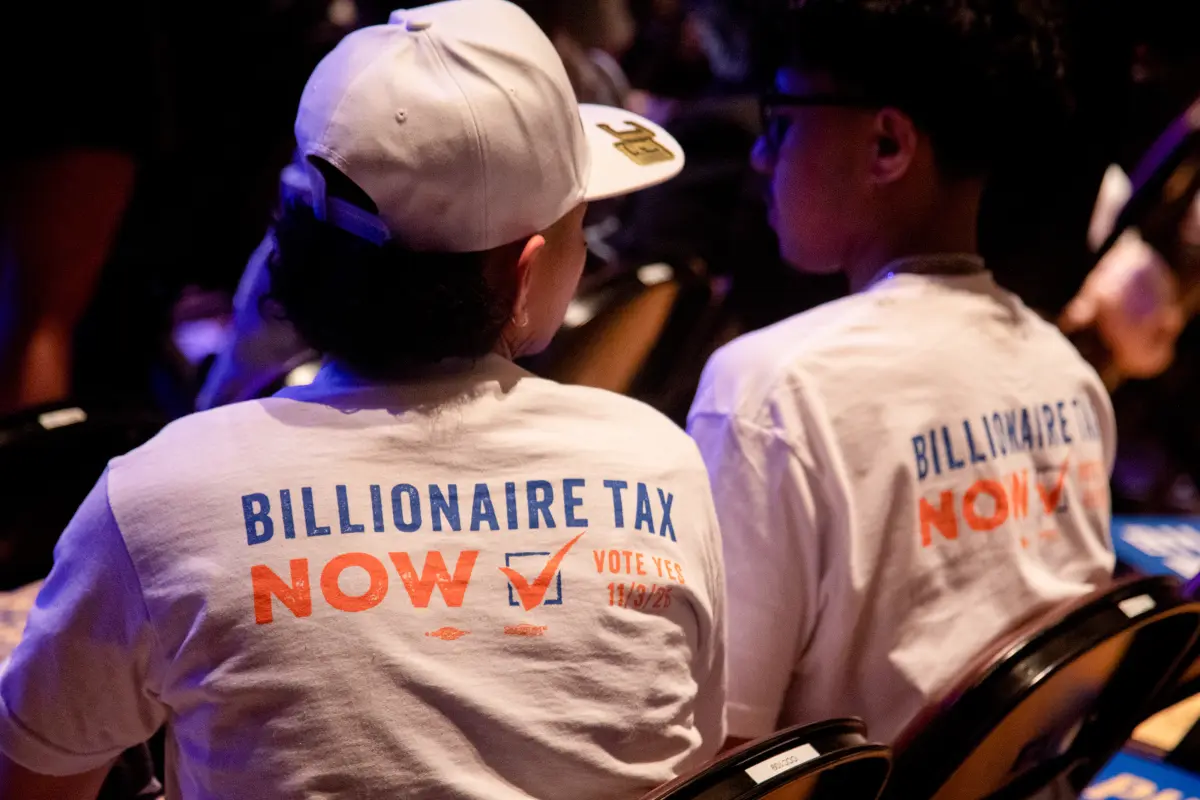
The proposed California billionaire tax is trailing as ballots from the November 3 election continue to be counted. In its November 6 update, ABC7 reported that 55 percent of voters opposed Proposition 40 and 45 percent supported it. The race had not been called as of that report.
The proposal has brought healthcare funding and California’s economic competitiveness into the same debate. Supporters argue that the state’s wealthiest residents should contribute more to protect healthcare services. Opponents, including Governor Gavin Newsom, have raised concerns about wealthy residents and businesses leaving the state. The outcome will determine whether California adopts this particular levy, while the arguments surrounding it highlight the competing demands facing a state with substantial public-service needs and a highly mobile pool of private wealth.
What the California Billionaire Tax Means for Family Offices
For family offices, the immediate implications center on liquidity, residency and the treatment of complex ownership structures. A tax on accumulated wealth reaches a different part of the family balance sheet from a tax on annual earnings. That makes the proposal relevant to decisions about concentrated company stakes, private investments and the cash available to meet obligations without disrupting a long-term investment strategy.
According to the state’s official voter guide, Proposition 40 would impose a one-time tax equal to 5 percent of net worth on billionaires who were California residents on January 1, 2026. Payment would be due in 2027, with an option to spread payments over five years at additional cost. Real estate, pensions and retirement accounts would generally be excluded. Ninety percent of the proceeds would support healthcare, with the remainder allocated to education, food assistance and administration.
The distinction between income and wealth is central. A founder can hold a multibillion-dollar company stake while receiving relatively modest annual cash income. A tax tied to that stake’s value presents a different problem from an income tax triggered by a sale. For a family office overseeing concentrated ownership, the question becomes how to meet a substantial obligation while preserving control, honoring existing commitments and avoiding an unfavorable sale.
Consider a simplified illustration: a 5 percent charge on $2 billion of covered taxable wealth would equal $100 million. Actual liabilities would depend on exemptions, valuation and other provisions. Still, the example explains why a seemingly modest percentage can reshape a family’s liquidity requirements. A portfolio worth billions is not necessarily a portfolio with hundreds of millions available for immediate withdrawal.
If Proposition 40 is ultimately rejected, the most immediate benefit would be the removal of that proposed demand on capital. Families that had incorporated a possible payment into their planning could revisit the associated reserves, borrowing arrangements or potential asset sales. Any adjustment would need to reflect the confirmed outcome and the family’s broader obligations. Money earmarked for a possible tax may also be supporting capital calls, operating businesses or spending commitments.
The episode also strengthens the case for treating liquidity as a family-wide responsibility. An investment team may see ample assets, while the treasury team sees restricted stock, pledged securities and private funds with uncertain distribution dates. A useful stress test brings those views together: what could the family actually access over 30 days, six months and a year? What would borrowing cost? Which sales would create additional taxes or compromise long-term holdings?
Residency is another central consideration for families with connections to California. Proposition 40’s January 1 reference date means that a move after the election should not be assumed to erase potential exposure if the measure ultimately passes. Separately, California’s existing income-tax framework continues to matter. The Franchise Tax Board taxes residents on income regardless of source, while nonresidents can still owe tax on California-source income, including income from California businesses and real estate.
The state’s residency guidelines examine connections such as homes, family, business interests and time spent in different locations. Moving a family office’s administrative address and changing a principal’s personal tax residency are separate questions.
The decision to stay also has a personal dimension. In Impact Wealth’s The Wealth of Staying with Olivier de Givenchy, the CEO of J.P. Morgan Private Bank’s West Region puts the family’s priorities at the center of the conversation. “The question is, where do they want to live?” he asks. His perspective encompasses where the next generation sees its future and what the family hopes to contribute to its community. For family offices, that means weighing potential tax savings alongside schools, relationships, business networks and the value of remaining rooted in a place.
Trusts deserve equally careful attention. The proposed law contains detailed provisions addressing grantor trusts, certain transfers and applicable trusts. Its structure illustrates why placing assets inside a trust cannot automatically be treated as protection from a new wealth levy. The planning implication is to maintain a clear ownership map: who owns each asset, who can benefit from it, who controls distributions and which jurisdictions have relevant connections. Those questions remain useful even if this proposal fails.
For investment committees, the broader issue is how to incorporate policy developments into portfolio decisions. The California proposal provides a concrete scenario for assessing concentration and cash needs. A useful review would examine the cost of raising liquidity, the timing of private-fund distributions and the flexibility available within existing credit arrangements. The objective is to identify decisions that support the family’s investment goals across several possible tax environments, with a clear understanding of the financial consequences of each.
The fiscal debate also warrants attention beyond its immediate effect on wealthy households. California’s legislative analyst estimated that the measure could generate tens of billions of dollars over several years, while behavioral responses could reduce ongoing income-tax revenue by less than $1 billion annually. The estimates capture the competing considerations: funding public services and maintaining a durable tax base. Neither side of that equation disappears with one election result.
The next step is to follow the remaining count and confirmed outcome, then reconcile any contingency plans with the family’s actual position. A defeat would provide meaningful relief from a specific proposed tax.