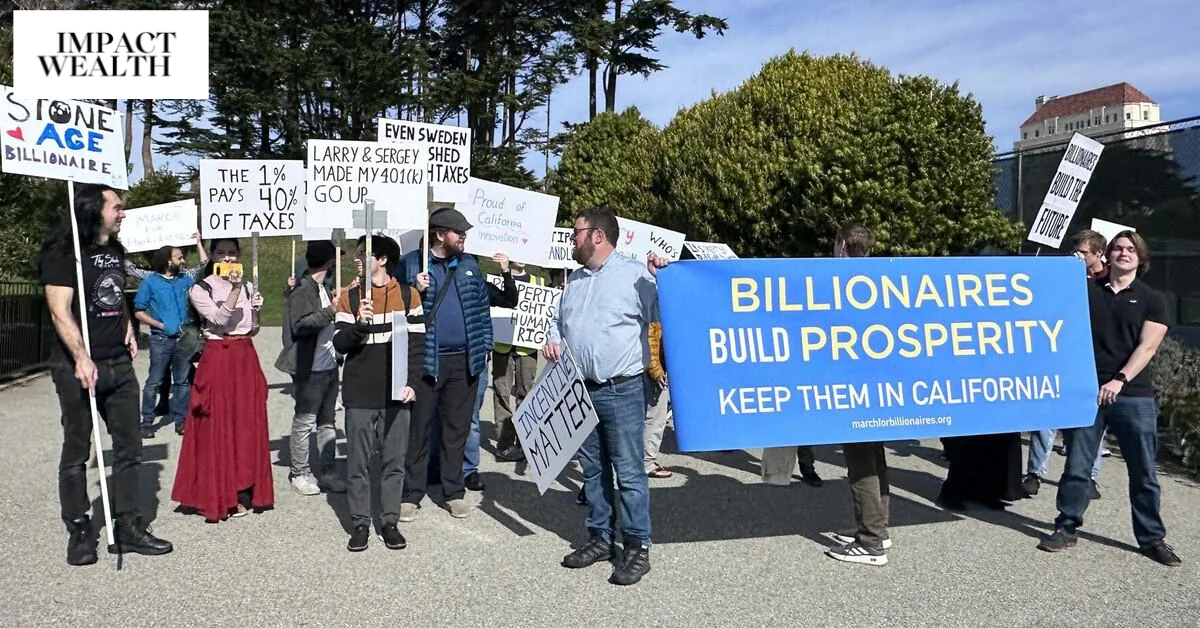
The California billionaire tax remains unresolved. Early returns showed Proposition 40 trailing, but ballots are still being counted. These are preliminary results, not a certified outcome, so this article does not treat the measure as defeated.
The vote still matters for planning. Whatever the final count, the campaign pushed families, family offices and advisers to ask where to live, hold entities and manage wealth, and what a move actually involves.
Important 2026 Update: One statewide election-night count put Prop 40 at about 43% yes; an earlier Chronicle tally showed it below 40%. The competing Props 41 and 42 ran ahead of it. Certification follows weeks after election day.
What California’s Billionaire Tax Vote Means
Proposition 40, the California billionaire tax, would impose a one-time 5% tax on the net worth of California residents worth $1 billion or more, applied to the whole fortune rather than the excess. Residency is fixed as of January 1, 2026, and net worth is measured on December 31, 2026. Payment can be spread over five years, with deferral charges. Roughly 200 to 250 people would be affected, and most proceeds would fund health care, including Medi-Cal.
Two measures complicate the result. Props 41 and 42, sponsored by a billionaire-funded committee, contain provisions that conflict with Prop 40. If either wins more yes votes, the tax cannot take effect, even if Prop 40 also passes. CalMatters reported roughly $317 million raised against Prop 40. Governor Gavin Newsom opposed it and endorsed Prop 42.
Why Billionaires Are Considering Leaving California
Three concerns drive the California billionaire tax debate. Exposure: 5% of a $100 billion fortune is $5 billion, and California already has the nation’s highest top income tax rate, 13.3% above $1 million. Valuation: net worth includes private companies and other illiquid assets that are hard to value and may force sales. Uncertainty: a one-time tax could set a precedent for later ones.
Legal questions add to it: the Tax Foundation argues the measure’s residency provisions are vulnerable to challenge. Departures are real but narrower than headlines suggest. Larry Page, Sergey Brin, Mark Zuckerberg and Peter Thiel have reportedly moved homes, offices or entities. Claims that $1 trillion of wealth has left come from advocates and are unverified, and some researchers say tax-driven migration among the very wealthy is limited.
Four States Attracting California’s Wealthy Residents
Florida. Florida has no individual income tax, barred by its constitution, and an established wealth-management community. Page reportedly spent $173 million on two Miami homes, Zuckerberg is reported to have bought a $170 million Miami mansion (Meta declined to confirm a residency change), and Thiel opened a Miami office. The trade-off is competition for premium property.
Texas. Texas also bars a personal income tax constitutionally and offers a business-friendly climate; David Sacks opened an Austin office. It raises revenue through property and sales taxes, with local sales tax reaching 8.25%, so large estates carry recurring costs.
Nevada. With no personal or corporate income tax and a border location, Nevada’s Lake Tahoe shore is the nearest alternative. Brin reportedly bought a roughly $42 million Tahoe house and moved entities to Nevada, and Steve Jurvetson paid a record $125 million for an Incline Village estate. A local broker says comparable homes can cost far more on the Nevada side, which can offset savings. Proximity also draws scrutiny: California’s tax agency has reportedly monitored Incline Village addresses. Buyers should study the local luxury real estate market closely.
Wyoming. Wyoming levies no individual or corporate income tax and no state estate or gift tax. Its pull is planning infrastructure: private family trust companies, directed trusts, dynasty trusts lasting up to 1,000 years, and strong privacy rules. A Wyoming trust can serve non-residents, but trust situs does not change an individual’s own residency. Jackson Hole supplies the lifestyle.
Tennessee and South Dakota also levy no individual income tax. Washington taxes capital gains, and Jeff Bezos moved to Florida after that tax was enacted, though he cites family and business reasons.
California vs. Other States: Tax and Lifestyle Comparison
| Factor | California | Florida | Texas | Nevada | Wyoming |
|---|---|---|---|---|---|
| Top individual income tax | 13.3% | None | None | None | None |
| Business environment | Deep talent and capital networks | Corporate income tax applies; growing finance community | No corporate income tax; franchise tax | No corporate income tax; Commerce Tax above a revenue threshold | No corporate income tax; small market |
| Estate-planning notes | Prop 40 pending | No state estate tax | No state estate tax | No state estate tax; trust-friendly | No state estate tax; dynasty trusts, private trust companies |
| Lifestyle | Coastal, tech hubs, high costs | Miami, Palm Beach; waterfront | Austin, Dallas; large cities | Lake Tahoe; near California | Jackson Hole; remote, outdoors |
Rates and rules change. Confirm each state’s figures with its revenue department. Federal taxes apply everywhere.
Why Changing Residency Is More Complicated Than Buying a New Home
Owning a house in another state, or spending time there, does not automatically make you a tax resident. California looks at where your closest connections are. FTB Publication 1031 describes weighing factors such as time in each state, where your spouse and children live, your principal residence, driver’s license, voter registration and business ties. You can keep several residences but only one domicile, and changing it takes both a move and the intent to stay, shown through actions.
Documentation matters: day counts, address changes, registrations, and where family, medical care and valuables are. Advisers report that audits can arrive years later, particularly after liquidity events, and that keeping a California family home or school ties can weaken a claim. They also cite a presumption of California residency for people present more than nine months a year.
Prop 40’s January 1, 2026 cutoff is separate from later moves. As drafted, someone who left after that date would still be treated as a California resident for the measure, if it takes effect and survives legal challenge. A later move affects future income-tax exposure, not that one-time liability. Relocation is never a guaranteed escape. Families should take legal and tax advice, including on mobility planning for children and other relatives.
What the Wealth Migration Could Mean for Businesses and Financial Markets
Estimates conflict. The Hoover Institution projected that permanent loss of income taxes from departing residents could leave the net effect negative by almost $25 billion. Economists Zucman, Boll and Saez estimated about $100 billion, after a 10% reduction for avoidance and earlier departures. California’s Legislative Analyst’s Office found a temporary revenue increase of up to tens of billions of dollars, alongside an ongoing income-tax decrease of hundreds of millions or more per year.
For business, moved entity registrations are not moved workforces. Page reportedly moved or closed more than 45 California LLCs and Brin 15. The more consequential shift may be where investment decisions are made, as founders such as Thiel and Sacks open offices elsewhere. So far the effects are most visible in Tahoe and Miami luxury markets, not in broad employment data.
Unique Insight: Is America’s Wealth Map Being Redrawn?
Partly, but through paper before people. Reported moves involve LLCs, family-office entities and trust situs as much as homes: Page reportedly converted his family office, Koop, from a California entity to a Delaware corporation with a Florida address. Tax policy appears to move entities and decision-making first, and households later, if at all.
The California billionaire tax also shows that a ballot measure can change behavior before it passes: many departures preceded the January 1, 2026 date. That could accelerate competition between states for founders and family offices. Yet a handful of high-profile moves among 200 to 250 billionaires is not a mass exodus, and evidence for broader groups is thin. If Props 41 or 42 prevail, the wealth-tax debate does not disappear. It becomes a template other states can copy or reject.
Conclusion
The final count will take weeks, and the lowest-tax destination is not automatically the right one. The California billionaire tax debate has shown that residency, entity location and family ties are planning decisions, not just tax ones. Whether Prop 40 passes or fails, families should map where they actually live, document it, and weigh costs, privacy, lifestyle and legal risk with qualified advisers before moving. States will keep competing for wealthy residents, and the durable plan is a flexible one.
FAQs
1. What happened in California’s 2026 billionaire tax vote?
Early returns showed Prop 40 trailing, with votes still being counted. Props 41 and 42, which could void it, ran ahead early. Results are preliminary until certified.
2. Where are California billionaires most likely to relocate?
Reported moves point mostly to Florida and Nevada, with Texas drawing offices. Wyoming appeals for trust and planning structures.
3. Why are wealthy residents considering Florida, Texas, and Nevada?
All three levy no individual income tax. Each adds something different: Florida’s wealth-management community, Texas’s business climate, Nevada’s proximity to California.
4. Does moving out of California eliminate billionaire tax liability?
No guarantee. Under Prop 40 as drafted, residency on January 1, 2026 controls, so the California billionaire tax, if enacted, could still reach later movers. Take legal advice.
5. How does California determine whether someone is a tax resident?
It weighs domicile and closest connections, including time in state, family, home, licenses and business ties.
6. Which states offer the most favorable tax environments for wealthy individuals?
Nine states have no broad individual income tax: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington and Wyoming. Property, sales, business and estate rules still matter.
7. Could billionaire relocation affect California’s economy and tax revenue?
Possibly. Estimates range from a roughly $25 billion net loss (Hoover) to about $100 billion in revenue (Zucman, Boll and Saez), so the effect is disputed.