Tuesday, November 17, 2026
  • Login
Subscribe
Impact Wealth
No Result
View All Result
  • Lifestyle
    • Health & Wellness
    • Fine Dining & Beverage
    • Fashion
    • Event Coverage
    • The Arts
    • Resources
  • Travel
  • Investing
    • Retirement
    • Real Estate
    • Philanthropy
    • Wealth
    • Business
  • Family Office News
  • Impact Interviews
  • Subscribe Now
  • About Us
    • Press
  • Join Our Community
  • Sign up for Newsletter
  • Lifestyle
    • Health & Wellness
    • Fine Dining & Beverage
    • Fashion
    • Event Coverage
    • The Arts
    • Resources
  • Travel
  • Investing
    • Retirement
    • Real Estate
    • Philanthropy
    • Wealth
    • Business
  • Family Office News
  • Impact Interviews
  • Subscribe Now
  • About Us
    • Press
  • Join Our Community
  • Sign up for Newsletter
No Result
View All Result
Impact Wealth
No Result
View All Result
Home Legal Rights

What Happens to Your Credit Score When Your Ex Stops Paying Shared Debts After Divorce?

by Allen Brown
November 2, 2026
in Legal Rights, Resource Guide
What Happens to Your Credit Score When Your Ex Stops Paying Shared Debts After Divorce?

Your credit score can drop if your ex stops paying shared debts after divorce, especially when both of you remain legally responsible for a loan or credit account. Missed payments, growing balances, and accounts sent to collections can damage your credit history even if your divorce agreement says your former spouse must make the payments. Creditors generally follow the original loan or account agreement, not the terms of your divorce decree.

Divorce can separate your financial responsibilities in court, but it does not automatically remove either person’s name from a joint debt. 

How long after divorce can you file bankruptcy? The answer may depend on how your divorce settlement divides debts, whether you can manage your current payments, and which bankruptcy option fits your financial situation.

This article explains how your ex’s missed payments can affect your credit after divorce and what steps you must take.

Lenders May Still Hold You Responsible for Shared Debts After Divorce

When you co-sign a loan or open a joint credit account, the lender may hold you responsible for the debt even after your marriage ends. If your ex misses payments, the lender may report the delinquency on your credit report as well.

This can happen with joint credit cards, personal loans, auto loans, and mortgages. A divorce decree may assign responsibility for a particular debt to your former spouse, but that assignment generally does not change the original contract with the creditor.

Under Florida Statutes § 61.075(3)(c), a contested divorce judgment must identify marital liabilities and specify which spouse is responsible for each liability. However, this allocation generally does not remove either spouse from a joint loan agreement with a creditor.

For example, if your divorce agreement requires your ex to pay a joint car loan and they stop making payments, the lender may still pursue you for the amount owed. Late payments can also remain on your credit report for years under applicable reporting rules.

Missed Payments and High Balances Can Lower Your Credit Score

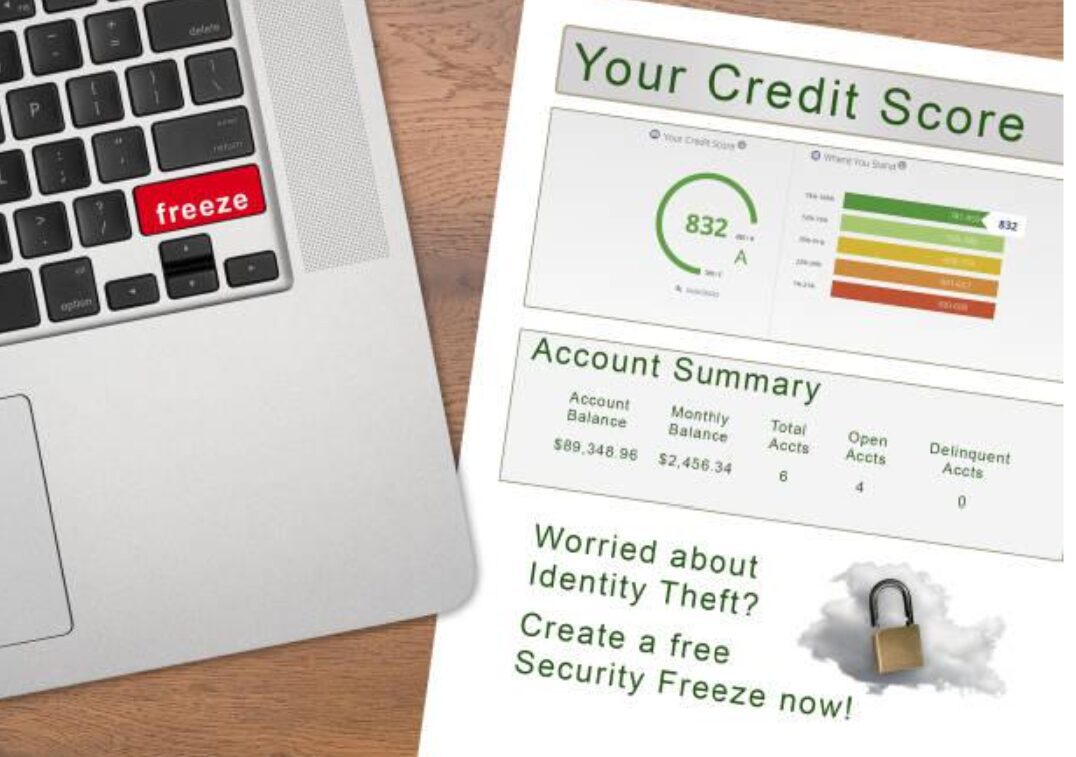
Payment history is an important factor in most credit scoring models. When a shared account becomes overdue, the creditor may report the missed payment to the credit bureaus, potentially lowering your score.

The impact depends on factors such as your existing credit history, the severity of the delinquency, and the scoring model being used. Repeated missed payments may cause more damage than an isolated late payment.

A high balance on a shared credit card can also affect your credit utilization ratio. Even if your ex is supposed to pay the bill, the outstanding balance may influence your credit profile while your name remains on the account.

Review your credit reports regularly so you can identify missed payments, incorrect balances, and other changes as soon as possible.

Steps to Protect Your Credit After Divorce

  • Contact the lender: Confirm the current balance, payment status, and options for removing your name from the account.
  • Explore refinancing: If your ex keeps a home or vehicle, refinancing may allow them to obtain a loan in their name alone, subject to lender approval.
  • Close or restrict joint credit accounts: Where permitted, ask the creditor about closing the account to new charges or taking other protective measures. Closing an account does not erase its existing balance.
  • Keep payment records: Save account statements, payment confirmations, and communications with your former spouse.
  • Check your credit reports: Review reports from the major credit bureaus and dispute inaccurate information with the relevant bureau and creditor.

If your ex violates the divorce agreement, a family law attorney may explain whether enforcement proceedings are available. 

When Bankruptcy May Become an Option

If shared debts and other financial obligations become unmanageable, bankruptcy may be worth discussing with a qualified attorney. Bankruptcy can provide relief from certain debts, but eligibility, available protections, and the consequences for joint borrowers depend on the circumstances and applicable law.

Key Points to Note

  • Your credit score may suffer if your ex stops paying debts that remain in both names.
  • A divorce decree does not automatically remove you from a joint loan or credit account.
  • Check your credit reports and contact lenders promptly when payments are missed.
  • Refinancing or formally removing a borrower may help separate financial responsibilities when the lender approves it.
  • Bankruptcy may be an option for overwhelming debt, but its effects on joint obligations require careful legal advice.
Previous Post

How Do DUI Accidents Involving Company Vehicles Impact Employer Liability?

Next Post

How Can Inflation and Future Earnings Impact the Assessment of Wrongful Death Compensation?

Related Posts

San Diego BK Review: Is It the Right Choice for a Business Bankruptcy Attorney in San Diego?
Business

San Diego BK Review: Is It the Right Choice for a Business Bankruptcy Attorney in San Diego?

November 16, 2026
What Investors Should Understand About the Risks Behind Private Credit Opportunities
Investing

What Investors Should Understand About the Risks Behind Private Credit Opportunities

November 12, 2026
The Hidden Cost of Pain: How Chronic Pain Affects Work & Quality of Life
Health & Wellness

The Hidden Cost of Pain: How Chronic Pain Affects Work & Quality of Life

November 16, 2026
The Hidden Financial Cost of a Serious Car Crash in Indiana, and How to Protect Your Household
Legal Rights

The Hidden Financial Cost of a Serious Car Crash in Indiana, and How to Protect Your Household

November 16, 2026
Realistic 3D Render of Office Interior
Real Estate

Unheard Phone Calls Are Costing Your Leasing Office Booked Tours

November 14, 2026
What Happens After an Arrest in Pasadena, California: A Practical Roadmap for the First Few Days
Legal Rights

What Happens After an Arrest in Pasadena, California: A Practical Roadmap for the First Few Days

November 14, 2026
Next Post
How Can Inflation and Future Earnings Impact the Assessment of Wrongful Death Compensation?

How Can Inflation and Future Earnings Impact the Assessment of Wrongful Death Compensation?

No Result
View All Result

Latest Stories

Manhattan Financial District skyline viewed from Brooklyn Heights.

Apollo Investment in Focus Financial Puts Adviser Ownership in Focus

Read More »
Elmer Heinrich Net Worth

Elmer Heinrich Net Worth in 2026: Business Career, Liquid Assets, and the Story Behind Immuno 150

Read More »
French Heritage Society Celebrates Craftsmanship and Culture at Le Bal Impérial in New York

French Heritage Society Celebrates Craftsmanship and Culture at Le Bal Impérial in New York

Read More »
8 Best Calgary Neighbourhoods for Real Estate Investors in 2027: Condos vs. Detached Homes

8 Best Calgary Neighbourhoods for Real Estate Investors in 2027: Condos vs. Detached Homes

Read More »
Impact Wealth Magazine

Impact Wealth is a luxury lifestyle magazine that caters to ultra-high net-worth individuals and the family office industry that features profiles on the world’s top business leaders and family offices, and investment strategies for the super rich.

Explore

  • Wealth
  • Net Worth
  • Investing
  • Family Office
  • Real Estate
  • Impact Investing
  • Philanthropy
  • Travel Lifestyle
  • Impact Leaders
  • Interviews

About Impact Wealth

  • Press
  • About Impact Wealth
  • Past Issues
  • Resources
  • Editorial Standards and Corrections

Stay Connected

Join Our Community

Sign up for our Newsletter

© 2026 ImpactWealth | Disclaimer & Privacy Policy

No Result
View All Result
  • Lifestyle
    • Health & Wellness
    • Fine Dining & Beverage
    • Fashion
    • Event Coverage
    • The Arts
    • Resources
  • Travel
  • Investing
    • Retirement
    • Real Estate
    • Philanthropy
    • Wealth
    • Business
  • Family Office News
  • Impact Interviews
  • Subscribe Now
  • About Us
    • Press
  • Join Our Community
  • Sign up for Newsletter

© 2026 ImpactWealth | Disclaimer & Privacy Policy

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Lifestyle
    • Health & Wellness
    • Fine Dining & Beverage
    • Fashion
    • Event Coverage
    • The Arts
    • Resources
  • Travel
  • Investing
    • Retirement
    • Real Estate
    • Philanthropy
    • Wealth
    • Business
  • Family Office News
  • Impact Interviews
  • Subscribe Now
  • About Us
    • Press
  • Join Our Community
  • Sign up for Newsletter

© 2026 ImpactWealth | Disclaimer & Privacy Policy